Declare Foreign Income to HMRC: Complete UK Tax Guide for 2026/27
September 22, 2026
Do I Need to Complete a Self Assessment Tax Return? 10 Common Reasons
September 24, 2026
How Much Can a Director Borrow From Their Limited Company? UK Guide for 2026/27
How Much Can a Director Borrow from a limited company? Learn the UK director’s loan rules, £10,000 benefit threshold, Section 455 tax, repayment deadlines, interest and practical examples for 2026/27.
How Much Can a Director Borrow from their limited company is a common question for owner-managed businesses, particularly where a director needs short-term access to company funds. A limited company can lend money to a director, but the withdrawal must be recorded correctly and may create tax consequences for both the company and the individual.
There is no single general tax rule that says a director can only borrow a fixed maximum amount. Therefore, when asking How Much Can a Director Borrow, the answer depends on the company’s finances, company law, the director’s loan account, the amount outstanding, how long it remains unpaid and whether interest is charged.
A director’s loan differs from salary, dividends or repayment of money previously lent to the company. Understanding How Much Can a Director Borrow is therefore only one part of the picture. Directors also need to understand when Section 455 tax arises, when a beneficial loan becomes taxable, and the consequences of leaving the balance outstanding.
This guide explains How Much Can a Director Borrow under the UK rules for 2026/27 and the practical points directors should consider before taking money from their company.
What is a director’s loan?
A director’s loan normally arises when a director takes money from the company that is not salary, a dividend, an expense reimbursement or repayment of money already owed to the director. The amount is usually posted to the director’s loan account, often called the DLA.
For example, if a director transfers £15,000 from the company bank account to their personal bank account and the payment is not salary or a lawful dividend, the company may treat the £15,000 as a loan. When considering How Much Can a Director Borrow, it is important to look at the running balance of the DLA rather than individual withdrawals in isolation.
The DLA may move between credit and debit during the year. A credit balance means the company owes the director money. An overdrawn or debit balance generally means the director owes the company money.
Good bookkeeping is essential because personal payments from the company account can increase the amount owed by the director.
How Much Can a Director Borrow from a limited company?
So, How Much Can a Director Borrow? From a tax perspective, there is no universal statutory maximum applying to every director’s loan. A company could potentially lend £5,000, £25,000, £100,000 or more, provided the transaction is legally valid and the company has sufficient resources.
However, How Much Can a Director Borrow should never be considered simply by looking at the cash in the bank. Directors have duties under company law and must consider the company’s financial position, its creditors and whether making the loan is in the company’s interests.
The amount also affects taxation. Once a beneficial loan exceeds £10,000 at any time during the tax year, employment-related benefit rules can become relevant. If the director is also a shareholder in a close company, an unpaid loan can also trigger Section 455 tax.
Therefore, the practical answer to How Much Can a Director Borrow is that there may be no simple numerical cap, but increasing the balance can increase tax exposure, reporting requirements and commercial risk.
Why the £10,000 figure matters
A frequent misunderstanding is that £10,000 is the maximum amount a director may borrow. It is not. When asking How Much Can a Director Borrow, the £10,000 figure is mainly important because of the beneficial loan rules.
Where the total outstanding balance on relevant beneficial loans does not exceed £10,000 at any time during the tax year, the small-loan exemption can normally prevent a taxable beneficial loan charge.
If the balance exceeds £10,000, even briefly, the exemption can be lost. This is why How Much Can a Director Borrow should be monitored throughout the year rather than only at the company’s year end.
For example, if a director’s balance is £9,800 for most of the year but rises to £10,500 for two weeks, the fact that it later falls below £10,000 does not automatically preserve the small-loan exemption.
How Much Can a Director Borrow without a benefit in kind will therefore depend not only on the closing balance but on the maximum balance outstanding during the tax year.
Section 455 tax and director’s loans
For many owner-managed companies, the biggest tax issue is Section 455 of the Corporation Tax Act 2010. This can apply where a close company lends money to a participator, which commonly includes a shareholder-director.
For loans made on or after 6 April 2026, the Section 455 rate is 35.75%. This is a company tax charge connected with the outstanding loan; it is not simply ordinary Corporation Tax on the company’s profits.
This is why How Much Can a Director Borrow can have a significant cash-flow impact. If £50,000 remains within the Section 455 charge, the potential tax can be £17,875.
The question How Much Can a Director Borrow should therefore be considered alongside the expected repayment date. A large loan repaid promptly may have very different tax consequences from the same amount left outstanding beyond the relevant deadline.
Importantly, Section 455 does not by itself convert the loan into salary or a dividend. It is a separate tax mechanism applying to relevant loans from close companies.
The nine-month-and-one-day deadline
The key deadline is generally nine months and one day after the end of the company’s Corporation Tax accounting period.
If the relevant director’s loan is repaid, released or otherwise dealt with before Section 455 becomes due, the company may avoid paying the Section 455 charge on the amount repaid, subject to anti-avoidance rules.
Suppose a company has a 31 March 2027 year end. An overdrawn director’s loan outstanding at that year end would normally need close attention before 1 January 2028.
When working out How Much Can a Director Borrow, directors should therefore know both the amount and the date. A £30,000 withdrawal shortly before year end may give far less time to deal with the balance than a withdrawal shortly after year end.
How Much Can a Director Borrow is consequently a cash-flow planning question as much as a tax question.
Example: £50,000 director’s loan
Now assume the director takes £50,000 and the full balance remains outstanding beyond the Section 455 payment deadline.
At a 35.75% Section 455 rate, the company could face a £17,875 tax charge. That is a substantial cash-flow cost even though the underlying £50,000 is still shown as money owed to the company.
If the loan is interest-free, there may also be a beneficial loan calculation.
This demonstrates why How Much Can a Director Borrow should not be determined simply by what the company can transfer. A company may physically have £50,000 available while still needing the cash for VAT, PAYE, Corporation Tax, suppliers, wages or future investment.
When assessing How Much Can a Director Borrow, directors should prepare a realistic company cash-flow forecast first.
Beware of repaying and immediately borrowing again
HMRC rules include anti-avoidance provisions designed to prevent directors from briefly repaying loans around the tax deadline and then withdrawing similar amounts again.
One rule can apply where repayments of more than £5,000 are linked with further borrowing of £5,000 or more within a 30-day period. There are also rules aimed at arrangements involving larger balances and an intention to redraw funds.
This means How Much Can a Director Borrow cannot sensibly be planned using a simple “repay today and borrow it back tomorrow” approach.
The facts and timing must be reviewed carefully. If a repayment is matched with new borrowing, relief from Section 455 may be restricted.
When discussing How Much Can a Director Borrow, directors should distinguish genuine repayment from temporary recycling of funds. Keeping a clear audit trail is particularly important where substantial sums are moving between the director and the company.
Paying interest to the company
A director can pay interest to the company on an overdrawn loan. Charging interest at least equal to the relevant official rate can reduce or eliminate the beneficial loan benefit, depending on the circumstances and whether the interest is actually paid within the required rules.
For 2026/27, the official rate is 3.75%.
This creates another dimension to How Much Can a Director Borrow. For example, a £100,000 interest-free balance produces a larger potential beneficial loan amount than a £15,000 balance.
Interest received by the company is normally company income and must be recorded correctly.
The question How Much Can a Director Borrow at a low tax cost therefore needs modelling. Paying interest may address the beneficial loan issue, but it does not automatically remove Section 455 if the relevant loan remains outstanding.
A written loan agreement can also help document the interest rate, repayment terms and commercial basis of a substantial advance.
Company law and approval requirements
Tax is only part of the issue. Companies Act requirements may apply to loans to directors, particularly larger loans.
Depending on the circumstances, member approval can be required before a company makes a loan to a director. There are statutory exceptions and specific rules, so substantial advances should be reviewed before funds are transferred.
This is another reason How Much Can a Director Borrow is not purely a tax calculation.
Directors also owe duties to the company. Withdrawing significant funds from a struggling company can create serious problems.
Before deciding How Much Can a Director Borrow, consider whether the company will remain able to pay employees, HMRC, suppliers, lenders and other creditors as liabilities fall due.
A director’s loan should never be used to disguise financial difficulty or extract cash that the business genuinely needs.
How Much Can a Director Borrow without paying Section 455 tax?
There is no single permanent “tax-free borrowing limit” for Section 455.
The £10,000 figure relates primarily to the beneficial loan exemption, not a blanket exemption from Section 455 for shareholder-directors.
How Much Can a Director Borrow without an eventual Section 455 payment depends heavily on whether the loan is within the charge and whether it is genuinely repaid within the relevant time limit.
A director could potentially borrow more than £10,000 and repay it before Section 455 becomes payable, although the beneficial loan rules may still need to be considered.
Equally, a smaller balance may create Section 455 consequences if it remains outstanding and the statutory conditions are met.
So when asking How Much Can a Director Borrow tax-free, separate the issues: benefit in kind, Section 455, personal tax, company law and repayment strategy.
How Much Can a Director Borrow is best answered after reviewing all five.
A simple way to assess the loan
A useful planning approach is to ask six separate questions. How Much Can a Director Borrow today? How Much Can a Director Borrow without disrupting company cash flow? How Much Can a Director Borrow before the £10,000 benefit threshold is crossed? How Much Can a Director Borrow and realistically repay? How Much Can a Director Borrow before Section 455 becomes material? Finally, How Much Can a Director Borrow while still leaving the company financially secure?
How Much Can a Director Borrow? Review the position regularly. How Much Can a Director Borrow? Recalculate before any withdrawal.
Common mistakes directors make
One common mistake is assuming company money belongs personally to the shareholder. A limited company is a separate legal entity.
Another is believing £10,000 is the absolute borrowing limit. It is not.
A third mistake is waiting until the accounts are prepared to ask How Much Can a Director Borrow, by which point the withdrawals have already happened and planning options may be limited.
Directors also sometimes declare dividends without checking distributable profits, or make a repayment shortly before a deadline with the intention of immediately borrowing the money again.
Another error is forgetting that the beneficial loan rules and Section 455 are separate. Paying interest may reduce the beneficial loan charge but does not necessarily solve the Section 455 position.
Good planning means asking How Much Can a Director Borrow before the transfer is made, not months later.
Frequently asked questions
When does a benefit in kind arise?
How Much Can a Director Borrow without a benefit depends on the balance. How Much Can a Director Borrow while using the small-loan exemption is normally limited to £10,000 throughout the tax year.
Is there a Section 455-free limit?
How Much Can a Director Borrow for Section 455 purposes has no universal tax-free limit. How Much Can a Director Borrow must be reviewed against the close-company rules and repayment timing.
Can the loan be interest-free?
How Much Can a Director Borrow interest-free depends on the beneficial-loan rules. How Much Can a Director Borrow above £10,000 may create a taxable benefit if insufficient interest is paid.
What if the company has cash?
How Much Can a Director Borrow is not decided by bank balance alone. How Much Can a Director Borrow should allow for tax, payroll, suppliers and other liabilities.
Can dividends clear the balance?
How Much Can a Director Borrow should not assume future dividends are guaranteed. How Much Can a Director Borrow against expected dividends requires sufficient distributable profits and proper approval.
What about short-term borrowing?
How Much Can a Director Borrow temporarily still needs tax review. How Much Can a Director Borrow shortly before year end may create different timing consequences.
Does paying interest solve everything?
How Much Can a Director Borrow is not increased by paying interest. How Much Can a Director Borrow while paying interest still needs a separate Section 455 review.
What about more than one company?
How Much Can a Director Borrow from multiple companies requires separate analysis. How Much Can a Director Borrow depends on each company, relationship, balance and relevant tax rule.
What if the company owes the director?
How Much Can a Director Borrow starts with the DLA balance. How Much Can a Director Borrow may be nil if payments are simply repaying money already owed to the director.
When is shareholder approval relevant?
How Much Can a Director Borrow can be affected by Companies Act requirements. How Much Can a Director Borrow without member approval depends on the facts and applicable statutory rules.
What is a safe borrowing level?
How Much Can a Director Borrow safely depends on affordability and repayment capacity. How Much Can a Director Borrow should also leave the company able to meet its liabilities.
Final thoughts
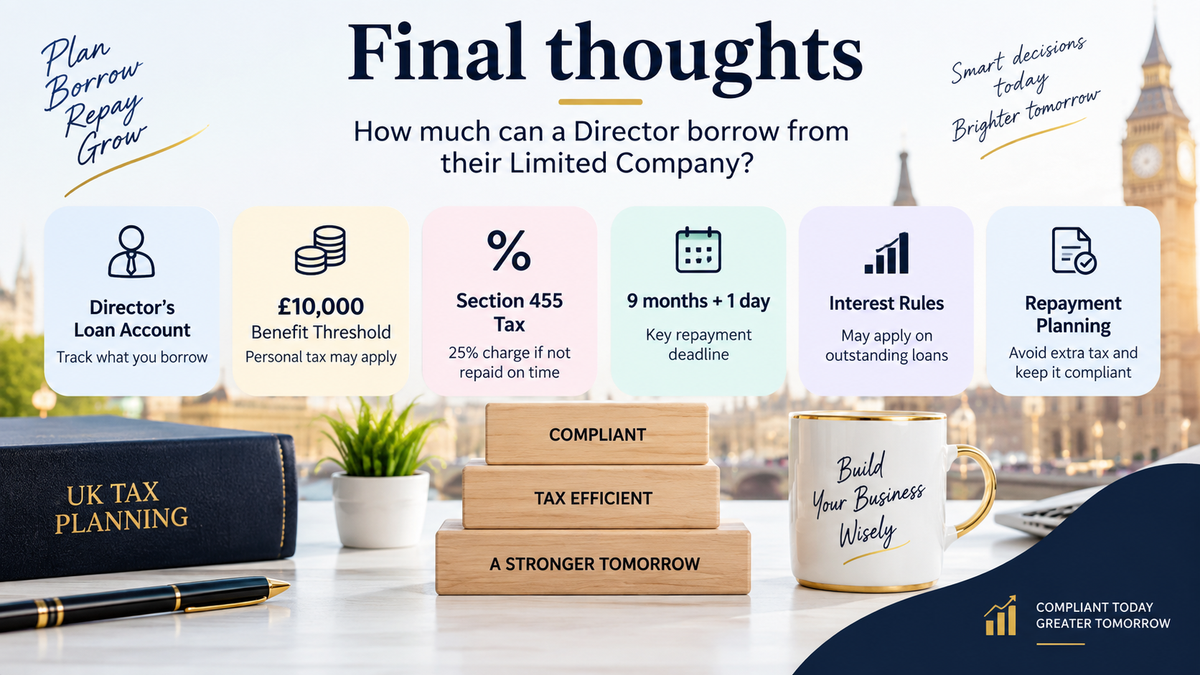
How Much Can a Director Borrow is not answered by one fixed statutory number. A limited company may lend substantial amounts to a director, but the bigger and longer the loan, the more important the tax, company law and cash-flow consequences become.
The £10,000 threshold matters for beneficial loans, while Section 455 can create a significant company tax charge where loans to shareholder-directors remain outstanding. For loans made from 6 April 2026, the Section 455 rate is 35.75%, and HMRC’s official beneficial-loan rate for 2026/27 is 3.75%.
If you are asking How Much Can a Director Borrow, first check the DLA balance, the company’s available cash, distributable reserves, repayment plan and year-end date.
How Much Can a Director Borrow safely is ultimately an individual calculation. A loan that is manageable for a profitable company with strong reserves may be inappropriate for a business with tight cash flow.
At Taxes Done Right Ltd, we can review the director’s loan account, calculate potential Section 455 and benefit-in-kind implications, and help plan withdrawals correctly before the tax cost becomes an unwelcome surprise. Careful planning can also protect working capital and reduce avoidable surprises.
If you want certainty over How Much Can a Director Borrow from your own company, take advice before transferring substantial funds and keep the position under regular review.
Need help deciding what’s best for your situation?
📞 Call 0161 710 1901
📧 Email Tax@TaxesDoneRight.co.uk
Visit www.taxesdoneright.co.uk