New to Self Assessment? Register by 5 October 2026 if you need to report income for 2025/26
September 28, 2026
Can You Claim the Cost of Replacing Windows in a Rental Property? UK Landlord Tax Guide
September 30, 2026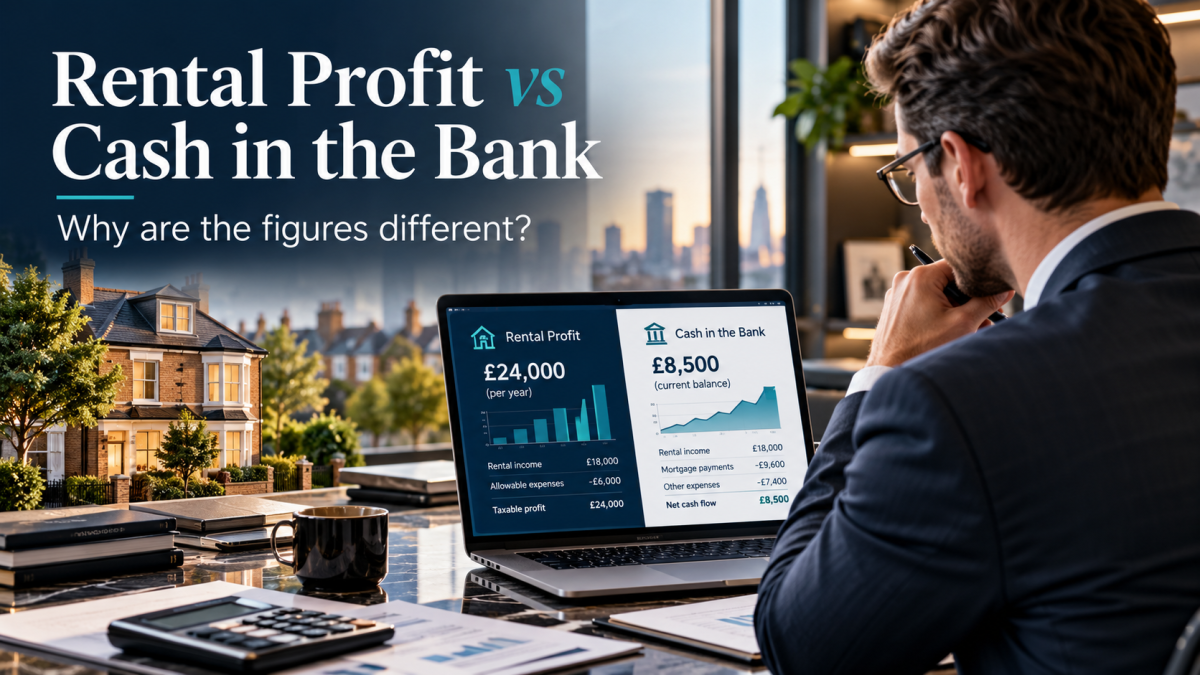
Rental profit versus cash in the bank: Why are the figures different?
Rental profit versus cash in the bank is one of the most common areas of confusion for landlords. You may look at your property account at the end of the year and feel that very little money remains, yet your Self Assessment calculation may show a healthy rental profit. The reverse can happen too: cash may have built up even though the taxable profit is lower.
The explanation is that Rental profit versus cash in the bank measures two different things. Your bank balance records money physically received and paid. Rental profit is a tax calculation based on taxable rental income less expenses that the tax rules allow you to deduct.
Understanding Rental profit versus cash in the bank matters because not every payment from a property account reduces taxable profit. Mortgage capital, capital improvements, private withdrawals and tax payments are obvious examples. Other costs, such as residential mortgage interest for individual landlords, can receive relief in a different way.
This guide explains it using practical UK landlord examples and shows why the taxable figure and the amount you feel you have actually made can be very different.
Rental profit versus cash in the bank: the basic difference
Rental profit versus cash in the bank starts with two separate calculations.
Cash movement is broadly the money received into the property business less the money actually paid out. Rental profit is broadly taxable rental income less allowable property expenses, subject to the tax rules and any separate adjustments or reliefs.
Rental profit versus cash in the bank therefore will not always match, because tax law does not treat every bank payment as a deductible expense.
It becomes particularly noticeable for landlords with repayment mortgages, major building works, managing agents, deposits or frequent personal transfers.
Why Rental profit versus cash in the bank can be so different
Several common items create the gap. Rental profit versus cash in the bank is normally explained by mortgage repayments, residential finance-cost rules, capital expenditure, timing, owner transfers, deposits and costs paid outside the main property account.
1. Mortgage capital repayments do not reduce rental profit
Mortgage repayments are one of the biggest reasons Rental profit versus cash in the bank differs.
The capital element reduces the amount you owe the lender. It is not an ordinary running expense of the rental business. As a result, it does not simply reduce taxable rental profit.
It can therefore look surprising. You may have £10,800 less cash after mortgage payments, but part of that money has gone towards reducing your debt rather than creating a deductible expense.
Rental profit versus cash in the bank will not treat the £3,000 capital repayment as a normal deduction. That is why landlords who are repaying debt quickly can feel cash-poor while still reporting taxable profit.
2. Residential mortgage interest has special rules
Rental profit versus cash in the bank is also affected by the residential property finance-cost restriction for individual landlords.
For an individual with residential property, qualifying mortgage interest is generally not deducted from rental income in the same way as ordinary running expenses. Instead, qualifying finance costs may give a basic-rate tax reduction, subject to the relevant limits.
Rental profit versus cash in the bank therefore should not be calculated by deducting the full mortgage payment from rent.
For tax purposes, Rental profit versus cash in the bank can show a much higher property profit before the finance-cost tax reduction is considered. This is one reason landlords sometimes say, “I did not make that much money, so why is my taxable rental profit so high?”
Rental profit versus cash in the bank can feel especially important for higher-rate and additional-rate taxpayers because the finance-cost restriction affects the way relief is delivered.
Limited companies have different rules, so Rental profit versus cash in the bank should not be analysed by copying the treatment used for personally owned residential property.
3. Capital improvements reduce cash but may not reduce current rental profit
Another major reason Rental profit versus cash in the bank differs is capital expenditure.
Ordinary repairs are generally treated differently from improvements. Capital expenditure is not normally deducted as a day-to-day rental expense.
Rental profit versus cash in the bank can therefore diverge sharply in a year when you renovate, extend or substantially improve a property.
Replacing broken roof tiles may be a repair. Adding another storey would clearly be an improvement. Many real-life cases sit between those examples, so the nature and extent of the work must be considered.
Rental profit versus cash in the bank also matters where a newly purchased property is in poor condition. Expenditure that feels like “repairs” in everyday language may sometimes be capital depending on the facts and the condition of the property when acquired.
4. Repairs and improvements need to be separated
Rental profit versus cash in the bank becomes easier to understand once repairs and improvements are recorded separately.
A repair normally restores an existing asset. Typical examples can include decorating, dealing with damp, repairing windows or replacing damaged roof components. An improvement goes further and enhances the property beyond its previous condition.
Rental profit versus cash in the bank differs because both repairs and improvements can reduce cash immediately, while their tax treatment may be different.
When reviewing Rental profit versus cash in the bank, good invoices are extremely useful. An invoice saying only “building work £8,500” gives far less evidence than one separating decoration, repairs, replacement items and improvement work.
Rental profit versus cash in the bank is therefore easier to reconcile when landlords keep detailed invoices, photographs where useful and clear descriptions of what work was completed.
5. The cash basis does not mean every cash payment is deductible
Many individual landlords use the cash basis, which can make Rental profit versus cash in the bank sound as though the figures should be identical.
Under the cash basis, property income and allowable expenses are broadly recognised when money is received or paid. However, the tax rules still decide whether a particular payment qualifies for a deduction.
Rental profit versus cash in the bank remains different because mortgage capital, private spending and non-deductible capital improvements do not become allowable simply because money left the bank.
The cash basis is mainly about when qualifying income and expenditure are recognised. It is not a rule saying every debit on your statement reduces taxable profit.
Rental profit versus cash in the bank should therefore be reconciled by category rather than by using the change in bank balance as the profit figure.
6. Money transferred by the landlord is not rental income
Rental profit versus cash in the bank can be distorted by owner transfers.
Suppose you transfer £5,000 of personal savings into the property account to pay for repairs or cover a mortgage payment. The bank balance increases, but you have not earned £5,000 of additional rent.
If you later withdraw £3,000 for personal use, the bank balance falls, but that withdrawal is not an allowable rental expense.
Rental profit versus cash in the bank will therefore differ whenever the owner introduces or withdraws personal money.
Rental profit versus cash in the bank is much easier to review if you operate a dedicated account for property transactions and clearly label any owner contributions or withdrawals.
7. Tenant deposits can affect the bank balance
Rental profit versus cash in the bank can also be affected by tenant deposits.
A tenancy deposit may pass through your account, but receiving money does not automatically make it rent. Deposits have their own legal treatment and, where required, must be dealt with under the relevant tenancy deposit protection rules.
Rental profit versus cash in the bank can therefore be misleading if deposits and rent are recorded together.
Keeping deposit transactions separate makes Rental profit versus cash in the bank easier to explain and reduces errors at year end.
8. Letting agents often pay you net, not gross
Rental profit versus cash in the bank is particularly important for landlords who use managing agents.
Suppose the agent collects £18,000 rent but deducts £1,500 management fees and £500 of repair costs before transferring £16,000 to you. Your bank statement shows only £16,000 arriving.
Rental profit versus cash in the bank should be reconciled to the agent statements so the gross rent and the relevant deductions are captured correctly.
Rental profit versus cash in the bank can also differ where the agent keeps money in a client account, pays contractors directly or carries forward a balance to the next month.
9. Expenses may be paid from another account
Rental profit versus cash in the bank can work in the opposite direction too.
You may pay building insurance from a personal credit card, buy repair materials from your personal current account or pay your accountant separately. If the costs are genuinely allowable property-business expenses, paying them from another account does not automatically make them irrelevant.
Rental profit versus cash in the bank therefore cannot always be calculated from one account alone.
Suppose the dedicated property account shows £10,000 cash surplus, but you personally paid £2,000 of allowable property expenses. The bank surplus does not capture those costs.
Rental profit versus cash in the bank should include a review of relevant personal payments, agent deductions and other accounts used for the property.
10. Replacement furniture and domestic items follow specific rules
Rental profit versus cash in the bank can differ when landlords buy furniture, appliances and other domestic items.
For qualifying residential lettings, tax relief may be available for the replacement of certain domestic items, subject to the conditions. The rules concern replacement, so a new purchase is not automatically treated in the same way merely because the item is used in the property.
Rental profit versus cash in the bank can therefore be affected when you buy a sofa, fridge, bed, curtains, carpet or similar item and assume that every pound paid is immediately deductible.
Rental profit versus cash in the bank becomes easier to support when invoices and notes clearly connect the new item to the old one.
11. Tax payments reduce cash but not rental profit
Income Tax is another major reason Rental profit versus cash in the bank differs.
If you pay £4,000 to HMRC, your cash falls by £4,000. That tax payment does not become an expense used to calculate the rental profit on which the tax is based.
Rental profit versus cash in the bank can look even more confusing where Self Assessment payments on account are due, because part of the cash payment may relate to the following tax year.
Rental profit versus cash in the bank is clearer if you maintain a separate tax reserve and treat HMRC payments separately from property operating expenses.
A practical Rental profit versus cash in the bank example
Consider an individual landlord with these annual figures:
Rent received: £24,000
Letting-agent fees: £2,400
Insurance: £500
Repairs: £1,600
Service charge and ground rent: £1,500
Mortgage payments: £12,000
Mortgage interest within those payments: £7,000
Mortgage capital within those payments: £5,000
Capital improvement: £4,000
Personal funds introduced by owner: £2,000.
Rental profit versus cash in the bank tells a different story. The £5,000 mortgage capital payment is not an ordinary deductible expense, the £4,000 capital improvement may not reduce current rental profit, and the £2,000 owner contribution is not rental income.
Rental profit versus cash in the bank therefore explains why a landlord can retain relatively little cash while still reporting a substantial taxable property profit.
This does not mean the tax calculation is claiming you physically kept £18,000. Rental profit versus cash in the bank simply reflects that taxable profit follows tax rules, whereas cash flow records money in and money out.
Timing can create further differences
Rental profit versus cash in the bank can also be affected by timing.
For landlords using the cash basis, qualifying receipts and expenses are generally recognised when received or paid. A payment just before or after 5 April can therefore fall into a different tax year.
Rental profit versus cash in the bank should be reviewed for the correct tax year rather than an arbitrary 12-month bank period.
Rental profit versus cash in the bank can also be affected by refunds, reimbursements and money held temporarily by an agent. Matching related transactions helps prevent misleading conclusions.
How to reconcile the two figures
Rental profit versus cash in the bank becomes much clearer when you perform an annual reconciliation.
Start with gross rent and other property receipts. Then identify allowable running expenses. Separately identify mortgage interest, mortgage capital, capital expenditure, deposits, owner transfers, tax payments and personal items.
Rental profit versus cash in the bank should then be compared by category, not by using one total.
A useful year-end checklist includes gross rents, agent fees, repairs, insurance, utilities, Council Tax, service charges, professional fees, replacement domestic items, finance costs, mortgage capital, improvements, deposits, owner contributions, withdrawals, refunds and HMRC payments.
Once those categories are separated, Rental profit versus cash in the bank usually becomes much easier to explain.
Rental profit versus cash in the bank is also easier to support where you retain invoices, receipts, letting-agent statements, tenancy records and evidence for major works.
Why both figures matter
Rental profit versus cash in the bank is not simply an accounting technicality.
Taxable profit helps determine your tax position. Cash flow tells you whether the property is generating enough money to cover mortgages, repairs, tax, void periods and future expenditure.
Rental profit versus cash in the bank therefore answers two different questions: “What profit is calculated under the tax rules?” and “How much cash has the property actually generated or consumed?”
Rental profit versus cash in the bank is particularly useful when considering rent levels, refinancing, overpayments, future repairs and whether enough cash should be retained as a reserve.
Final thoughts
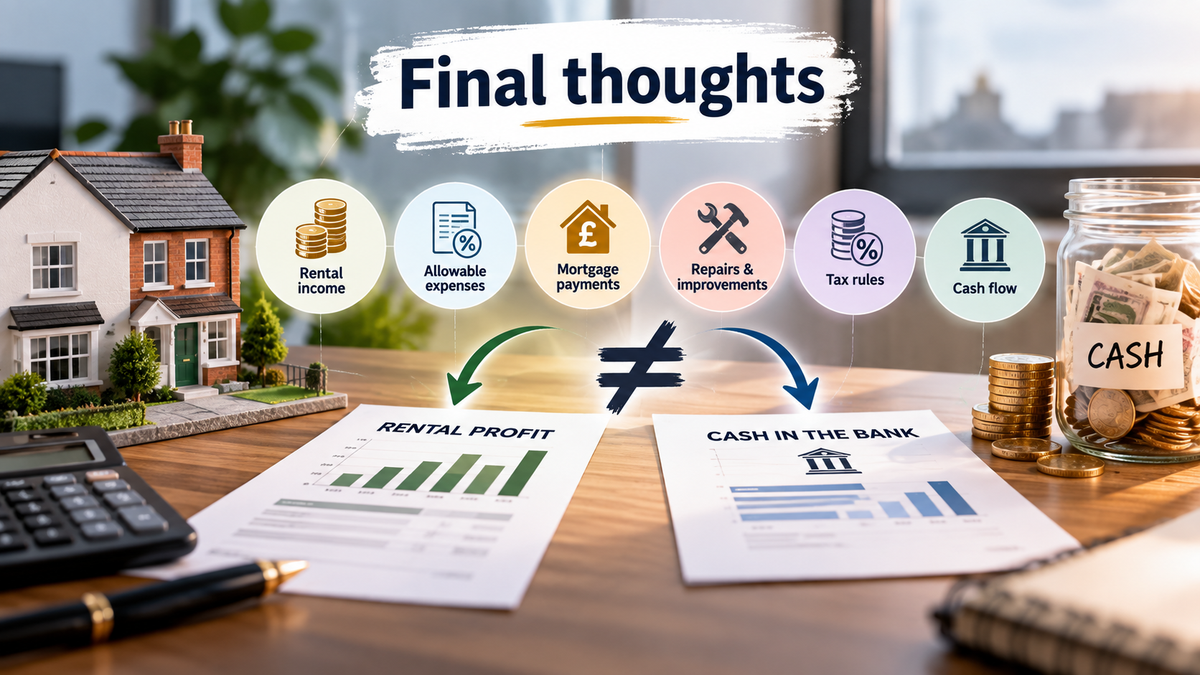
Rental profit versus cash in the bank is different because taxable property profit is not calculated simply by checking what remains in your bank account.
Rental profit versus cash in the bank can also work the other way where property expenses are paid personally or a managing agent deducts costs before sending the remaining rent to you.
The best approach is to maintain clear records, reconcile gross rental income, distinguish repairs from capital improvements, review mortgage statements and identify personal transfers separately.
Rental profit versus cash in the bank becomes much less confusing once you recognise that one figure measures taxable performance and the other measures cash movement.
If your rental accounts show a profit that does not resemble your bank balance, Taxes Done Right Ltd can review your rental income, expenses, mortgage costs and supporting records, explain the differences and help ensure the figures are reported correctly.
Rental profit versus cash in the bank should be understood before making tax, refinancing or investment decisions, because the taxable profit and the money available to spend are not the same thing.
Rental profit versus cash in the bank can look very different because taxable profit is based on tax rules, not simply on the amount left in your bank account.
Mortgage capital repayments, property improvements, personal withdrawals and tax payments can reduce your cash without reducing your taxable rental profit. At the same time, some allowable expenses may be paid from another account or deducted by your letting agent before the rent reaches you.
Keeping clear records and separating cash-flow items from tax-deductible expenses makes your rental accounts much easier to understand.
If your rental profit does not seem to match the cash you have actually received, Taxes Done Right Ltd can help review the figures and explain exactly where the difference comes from.
Need help deciding what’s best for your situation?
📞 Call 0161 710 1901
📧 Email Tax@TaxesDoneRight.co.uk
Visit www.taxesdoneright.co.uk