Year-end accounts: a checklist for small business owners
November 4, 2026
Trivial benefits: small gifts for employees and directors
November 6, 2026
Family Investment Companies: benefits, costs and common misconceptions
Managing family wealth is not simply about growing investments. It also involves protecting assets, planning for future generations, controlling taxation and ensuring wealth passes to the right beneficiaries.
For families holding substantial investments, property portfolios or accumulated business profits, Family Investment Companies have become an increasingly discussed option for long-term wealth management.
But are they genuinely tax-efficient? How much do they cost? And can they really help reduce inheritance tax?
Although Family Investment Companies can offer valuable planning opportunities, they are frequently misunderstood. They are not automatic tax shelters, and their advantages depend heavily on personal circumstances, investment objectives and the way they are structured.
In this guide, we explain how Family Investment Companies operate in the UK, explore nine potential benefits, examine the costs involved and address common misconceptions that could lead to expensive mistakes.
1. What Are Family Investment Companies?
Family Investment Companies (FICs) are private limited companies established primarily to hold, manage and grow family wealth.
Unlike ordinary trading companies, their principal purpose is generally investment rather than selling products or providing commercial services.
A FIC might hold assets such as:
- Investment properties and rental portfolios.
- Shares in listed or private companies.
- Cash deposits and other financial investments.
- Investment funds and diversified portfolios.
- Certain other assets intended for long-term growth.
The company is usually owned by family members, with parents or grandparents acting as directors and potentially holding different classes of shares from their children.
This creates opportunities to separate management control from economic ownership.
For example, parents might retain voting control while adult children own shares participating in future investment growth.
However, shares must carry genuine legal and economic rights. Simply allocating shares to relatives does not automatically remove wealth from an individual’s estate.
The effectiveness of any arrangement depends on the company’s Articles of Association, share rights, funding arrangements and tax treatment.
2. How Do Family Investment Companies Work?
A FIC operates under the same fundamental company law framework as other UK private limited companies.
It is incorporated at Companies House, appoints directors, issues shares and maintains accounting records.
Family members can introduce capital through share subscriptions or loans, subject to appropriate documentation.
Once funded, the company invests according to its agreed strategy.
Investment profits may be retained for reinvestment, while distributions to shareholders can be considered when appropriate.
A simple example
Consider parents with £1 million available for investment.
Rather than holding every investment personally, they establish a FIC and introduce £1 million through a properly documented shareholder loan.
The company then invests the funds in a diversified portfolio.
The parents may retain voting control, while a separate class of shares allows adult children to benefit from future growth.
The shareholder loan remains an asset belonging to the parents unless subsequently repaid, gifted or otherwise dealt with.
Therefore, the original £1 million does not automatically disappear from their estates.
This distinction is critical.
Family Investment Companies are typically designed around long-term ownership, investment management and succession planning, not instant tax elimination.
3. Nine Potential Benefits of Family Investment Companies
Benefit 1: Long-Term Inheritance Tax Planning
One of the principal reasons families consider a FIC is the potential to manage future inheritance tax exposure.
Under current UK rules, inheritance tax is generally charged at 40% on the taxable estate above applicable allowances.
The standard nil-rate band is £325,000, with an additional residence nil-rate band potentially available where qualifying conditions are satisfied.
Through careful share structuring, some future investment growth may accrue to younger family members rather than remaining entirely within the older generation’s estates.
Where shares are genuinely gifted to individuals, the seven-year inheritance tax rule may be relevant.
However, gifts must be effective, and retained benefits can undermine the intended treatment.
Transferring shares into trusts can also trigger different inheritance tax consequences.
Professional valuation and succession advice are therefore essential before implementing the arrangement.
Benefit 2: Retaining Management Control
A significant attraction of Family Investment Companies is the ability to retain control over investments while allowing other family members to participate economically.
Different share classes can carry different voting, dividend and capital rights.
For example, parents might hold voting shares, allowing them to continue making decisions about investment strategy and company management.
Their adult children might hold non-voting shares entitled to participate in investment growth.
This arrangement may provide a more structured alternative to transferring assets directly into children’s personal ownership.
Nevertheless, directors must act in accordance with company law and their legal duties.
Family control cannot override shareholders’ rights or justify the personal use of company assets without appropriate treatment.
Benefit 3: Potentially Efficient Reinvestment
A FIC can provide a structure for retaining investment returns and reinvesting them over many years.
Where profits are retained within the company, personal dividend taxation is generally deferred until taxable distributions are made.
This may allow more capital to remain invested compared with arrangements requiring regular personal withdrawals.
However, the corporation tax position must be examined carefully.
Many FICs qualify as close investment-holding companies and are subject to the 25% main corporation tax rate, without access to the 19% small profits rate or marginal relief.
Furthermore, many qualifying UK and overseas corporate dividends are exempt from corporation tax when received by a UK company, although exceptions apply.
This makes the type of investment income particularly important.
Reinvestment benefits must ultimately be measured against future shareholder taxes and administrative expenses.
Benefit 4: Flexible Share Ownership
Family Investment Companies may use different share classes to reflect family objectives.
These can potentially include:
- Voting shares for management decisions.
- Non-voting shares for family beneficiaries.
- Shares with differing dividend entitlements.
- Shares with different capital participation rights.
Such arrangements provide flexibility in designing a long-term ownership structure.
However, issuing multiple share classes does not guarantee a tax advantage.
Rights must be legally documented, supported by commercial reasoning and reviewed for potential anti-avoidance, settlement and valuation issues.
Particular care is required where shares are allocated to spouses or minor children.
Benefit 5: Structured Wealth Succession
A FIC can help families formalise how investments are managed across generations.
Rather than leaving beneficiaries to manage a collection of separately owned assets, investments can remain within one company.
This may help establish clear governance, decision-making arrangements and succession procedures.
Families can create shareholder agreements covering matters such as future ownership transfers, dividend policies and disagreements.
Succession arrangements can also consider what happens if a director retires, dies or becomes unable to manage the business.
The result may be greater continuity, although successful succession still requires appropriate estate planning.
Benefit 6: Asset Administration and Organisation
Holding multiple investments through one company can simplify certain aspects of administration.
A FIC may maintain centralised investment records, financial statements and management reporting.
This can be particularly attractive where several family members have an interest in a substantial portfolio.
However, administrative consolidation should not be confused with guaranteed asset protection.
Company assets may still be exposed to investment losses, creditors, litigation and other commercial risks.
The company also has filing, governance and disclosure responsibilities.
Benefit 7: Potential Dividend Planning
A properly structured FIC may distribute profits to different shareholders according to their legal entitlements.
Where adult family members have different income levels, this may create opportunities for legitimate family-wide tax planning.
Nevertheless, distributions cannot simply be allocated arbitrarily.
The company must have sufficient distributable reserves, and dividends must comply with the rights attached to each share class.
The UK dividend tax rules also mean shareholders may incur personal income tax on amounts received.
For 2026/27, dividend tax rates are 10.75%, 35.75% and 39.35%, depending on the individual’s tax band.
A FIC should not be established solely on the assumption that family dividends will always be taxed more favourably.
Benefit 8: Separation of Investment and Personal Assets
A company can provide a clear distinction between investments owned personally and those legally owned by the investment company.
This may support accounting transparency, succession planning and investment governance.
For families with substantial business interests, a separate investment structure may also help distinguish personal wealth management from trading activities.
However, transferring existing investments into a FIC can create immediate tax liabilities.
Capital gains tax, stamp duties and other transaction costs must be considered before moving assets.
The safest structure is not necessarily the one involving the greatest number of companies.
Benefit 9: Building a Long-Term Family Investment Strategy
Perhaps the most valuable non-tax benefit is the opportunity to establish a disciplined investment strategy.
Families can agree investment objectives, acceptable risks, reinvestment policies and circumstances in which funds may be withdrawn.
This approach may discourage short-term financial decisions and encourage greater involvement from future generations.
A well-managed FIC can therefore operate as a long-term investment vehicle rather than merely a tax-planning arrangement.
However, the investment strategy remains subject to market conditions, liquidity requirements and the financial circumstances of individual family members.
4. Understanding the Tax Treatment of Family Investment Companies
Taxation is one of the most misunderstood aspects of Family Investment Companies.
There is no special universal FIC tax rate.
Instead, tax depends on the company’s activities, the income generated, the ownership structure and how shareholders access their investments.
Corporation Tax
For 2026/27, the standard UK corporation tax framework includes a 19% small profits rate and a 25% main rate.
However, companies classified as close investment-holding companies generally pay corporation tax at 25% on taxable profits, regardless of whether those profits fall below £50,000.
HMRC explains this distinction in its close investment-holding company guidance.
Certain property investment companies may fall outside this classification where the statutory conditions are satisfied.
Consequently, each FIC must be assessed individually.
Capital Gains
Where a FIC sells an investment at a gain, the taxable chargeable gain generally falls within corporation tax.
Companies do not benefit from the annual capital gains exemption available to individuals.
This distinction can affect the overall return from long-term investments.
Dividend Income
Many dividends received from qualifying corporate investments may be exempt from corporation tax.
However, dividends subsequently paid by the FIC to individual shareholders can produce personal dividend tax liabilities.
Families must distinguish between income received by the company and income extracted from it.
Inheritance Tax
Inheritance tax planning depends on the value and ownership of shares, shareholder loans, gifts and retained benefits.
The company itself does not automatically provide inheritance tax exemption.
5. How Much Does a Family Investment Company Cost?
Establishing and maintaining a FIC can be considerably more expensive than operating a straightforward investment account.
Costs vary depending on the number of shareholders, asset values, share classes and level of legal and tax advice required.
The following are illustrative professional fee ranges, not fixed market prices.
| Cost | Indicative amount |
|---|---|
| Initial company incorporation | £100 Companies House online fee |
| Specialist legal and tax structuring | £2,000–£10,000+ |
| Shareholder agreements and documentation | £500–£3,000+ |
| Share valuation, if required | £500–£3,000+ |
| Annual accounting and corporation tax compliance | £1,000–£3,000+ |
| Annual legal or tax reviews | Variable |
| Confirmation statement | £50 online |
The statutory fees are based on published Companies House fees. Professional fee estimates are indicative and will depend on individual requirements.
More complex arrangements may cost significantly more.
Additional expenses can include investment management fees, banking charges, property transaction costs and professional valuations.
For smaller investment portfolios, these expenses may outweigh the potential advantages.
Families should therefore assess expected long-term financial benefits before committing to the structure.
6. Family Investment Companies and Property Investment
Property investors frequently ask whether a FIC can be used to hold existing rental properties.
The answer is yes, but the tax consequences require particular attention.
Where personally owned properties are transferred into a connected company, capital gains tax may arise based on market value, even where little or no cash changes hands.
Stamp Duty Land Tax may also apply.
HMRC’s property transfer guidance explains that transfers to connected companies can be assessed using market value.
Mortgage arrangements, lender approval, legal fees and existing borrowing must also be reviewed.
A FIC holding residential property may therefore face substantial upfront costs.
Families investing in new properties may have different planning opportunities from those transferring an established portfolio.
It is also important to distinguish between companies holding investment portfolios and companies carrying on qualifying property letting activities.
Their corporation tax classification may differ.
7. Seven Common Misconceptions About Family Investment Companies
Misconception 1: A FIC Automatically Eliminates Inheritance Tax
False.
A FIC does not automatically remove assets from an individual’s taxable estate.
Share ownership, shareholder loans and retained economic interests all require consideration.
Potential inheritance tax advantages arise from effective planning, not simply company incorporation.
Misconception 2: Every FIC Pays Only 19% Corporation Tax
False.
Many FICs are close investment-holding companies and pay corporation tax at the 25% main rate on taxable profits.
Assuming the small profits rate applies can lead to inaccurate tax projections.
Misconception 3: Money Can Be Withdrawn Tax-Free Whenever Needed
False.
Payments to shareholders must have an appropriate legal and tax basis.
Dividends may create personal income tax liabilities.
Loan repayments may be tax-neutral to the extent they genuinely repay outstanding loan principal, but interest, benefits and other payments can have different consequences.
Misconception 4: FICs Are Only Suitable for Millionaires
Not necessarily.
There is no general statutory minimum investment amount required to establish a FIC.
However, professional fees and ongoing administration mean the structure is usually more attractive where substantial assets and long-term objectives justify its cost.
Misconception 5: Family Members Can Receive Any Dividend Amount
Not automatically.
Dividends must follow share rights and company law requirements.
Creating multiple share classes may provide flexibility, but distributions must be properly authorised and documented.
Misconception 6: Transferring Existing Assets Is Tax-Free
False.
Transferring properties, shares or other investments into a company may trigger capital gains tax, stamp duties or other liabilities.
The original ownership position and market value of the assets must be examined.
Misconception 7: A FIC Is Always Better Than a Trust
False.
Trusts and Family Investment Companies serve overlapping but distinct purposes.
Trusts may offer particular protections and succession mechanisms, while FICs provide a corporate investment and governance framework.
Some families may benefit from combining structures, while others may require neither.
The correct choice depends on personal circumstances.
8. Family Investment Companies vs Family Trusts
Families often compare a FIC with a discretionary trust.
Both can support succession planning, but their structures and tax treatment differ.
| Feature | Family Investment Company | Family Trust |
|---|---|---|
| Legal structure | Limited company | Trust arrangement |
| Management | Directors | Trustees |
| Ownership | Shareholders | Trustees hold assets for beneficiaries |
| Taxation | Corporate tax rules | Trust tax rules |
| Succession | Share transfers and governance | Trust deed and trustee decisions |
| Ongoing compliance | Company filings and tax returns | Trust administration and applicable reporting |
Neither arrangement is automatically superior.
A trust may be suitable where control over beneficiaries and asset protection are primary objectives.
A FIC may be preferable where the family wants an investment vehicle with defined shareholdings and company governance.
Specialist advice should assess the inheritance tax, capital gains tax and ongoing compliance implications of both.
9. Who Should Consider a Family Investment Company?
A FIC may be worth exploring for families with substantial accumulated wealth and a clear intention to invest over the long term.
Potential candidates include business owners with significant investment capital, property investors planning future acquisitions and families seeking structured succession arrangements.
However, FICs may be less appropriate where individuals need regular access to investment income, have comparatively modest assets or want simple administration.
The timescale matters considerably.
A structure intended to operate over several decades should be assessed differently from one established for short-term tax savings.
The ages of beneficiaries, existing estate plans and likely future expenditure are also important.
10. How to Set Up a Family Investment Company
Establishing a FIC should begin with a review of the family’s financial circumstances rather than immediate company incorporation.
A typical process involves:
- Reviewing family wealth: Identify existing investments, liabilities, inheritance tax exposure and long-term objectives.
- Assessing tax consequences: Consider corporation tax, capital gains tax, inheritance tax and potential transaction costs.
- Designing the share structure: Determine voting rights, economic entitlements and succession arrangements.
- Preparing legal documentation: Establish suitable Articles of Association, shareholder agreements and any loan agreements.
- Incorporating and funding the company: Complete registration, banking arrangements and properly documented funding transactions.
- Maintaining ongoing compliance: Prepare accounts, corporation tax returns, confirmation statements and appropriate investment records.
Careful implementation helps ensure the company’s legal structure reflects the family’s actual intentions.
11. Common Mistakes to Avoid
One common mistake is focusing entirely on inheritance tax without calculating the overall tax position.
For example, potential estate planning savings may be offset by corporation tax, dividend tax or substantial asset transfer costs.
Another mistake is introducing complicated share classes without understanding their legal consequences.
Poorly drafted share rights can create disagreements or unexpected tax results.
Families should also avoid mixing personal and company expenditure, failing to document loans or assuming that investments held within a company are automatically protected from creditors.
Finally, succession arrangements should be reviewed regularly.
Changes in family relationships, financial objectives or tax legislation may affect whether the original structure remains suitable.
12. Are Family Investment Companies Worth It in 2026?
The answer depends on the family’s objectives, financial resources and intended investment period.
For some families, a carefully designed FIC can offer an effective combination of investment management, governance and long-term succession planning.
For others, direct ownership, pension contributions, ISAs, trusts or conventional estate planning may produce better outcomes at lower cost.
The key is to compare realistic alternatives using projected investment returns, taxes, professional costs and inheritance outcomes.
A Family Investment Company should be judged by its overall financial and succession benefits, not by an isolated headline tax rate.
Final Thoughts
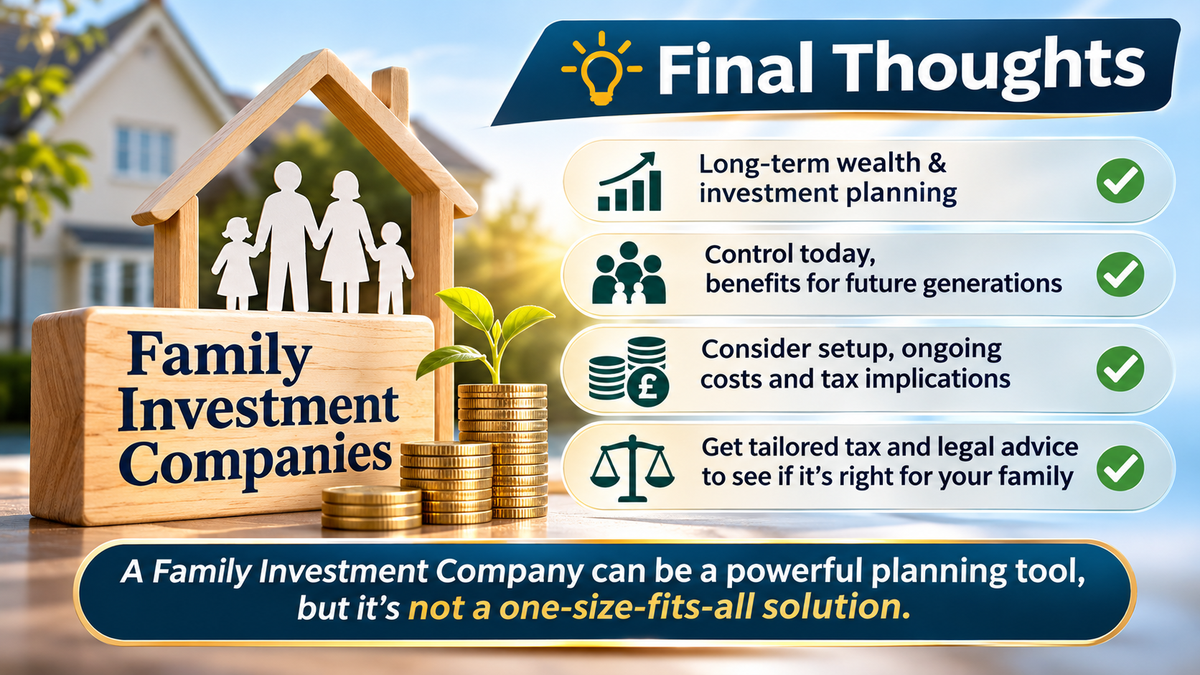
Family Investment Companies can provide valuable opportunities for families looking to manage investments, retain control and plan how wealth passes between generations.
Their potential benefits include structured ownership, long-term reinvestment, succession planning and possible inheritance tax advantages.
However, they also involve establishment costs, ongoing compliance responsibilities, complex tax rules and potential difficulties when extracting funds.
The biggest misconception is that establishing a Family Investment Company automatically reduces tax. In reality, the benefits depend on how the structure is funded, owned, operated and maintained.
Before proceeding, families should obtain tailored tax and legal advice to ensure the arrangement is commercially sensible and aligned with their long-term objectives.
How Taxes Done Right Can Help
At Taxes Done Right Ltd, we help individuals, business owners, landlords and investors understand their UK tax obligations and explore appropriate tax-planning options.
Whether you are considering a Family Investment Company, reviewing an existing investment structure or planning how to pass wealth to the next generation, our team can help assess the potential tax implications.
For professional UK tax advice:
📞 Call: 0161 710 1901
📧 Email: Tax@TaxesDoneRight.co.uk
Visit: www.taxesdoneright.co.uk
Get professional support to ensure your business expenses are recorded correctly and your tax position is managed efficiently.